01 Live well.
Homes planned for household affordability, comfortable living and practical daily needs.
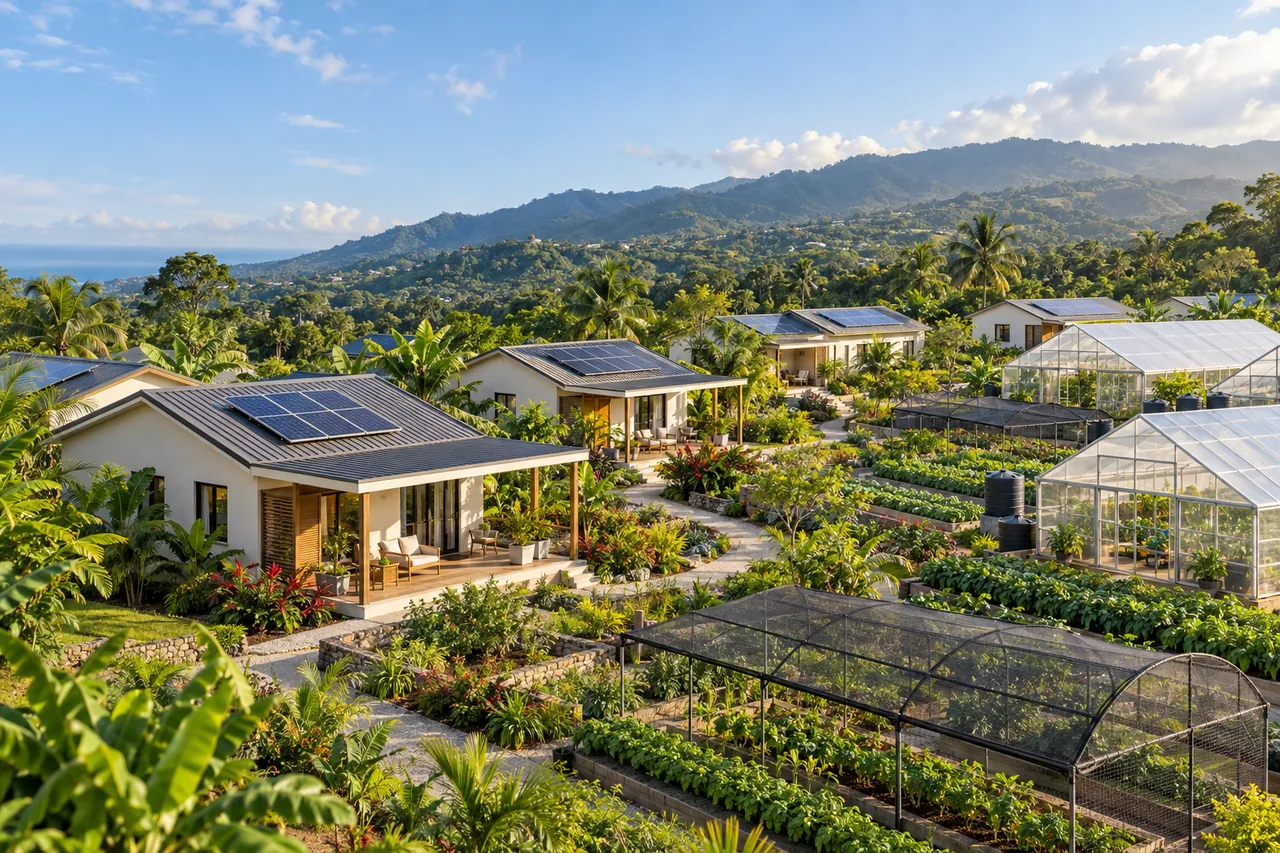
Jamaica · Housing & productive growing
Affordable homes, protected growing, solar energy and water infrastructure. A proposed community planned around everyday life.
Concept rendering · Not an actual site or approved design.
Proposed development · Feasibility stage
Homes planned for household affordability, comfortable living and practical daily needs.
Protected growing for willing operators, with agricultural roles separate from home ownership.
Water, energy and shared services considered as part of a connected development.
No construction date is set. Homes are not yet for sale.
01 / The need
Jamaica needs more homes that households can afford. NHT identifies a gap between housing demand and supply in its own development programme. Our proposal addresses the cost of a home alongside income-generating agriculture and the energy and water services needed for daily life. [3]
A purchase price must fit the buyer’s deposit and confirmed borrowing capacity. Mortgage payments, insurance, utilities, maintenance and estate charges must also leave enough for daily living.
Jamaican context: the Government’s June 2025 announcement provides up to J$12m for a single NHT applicant buying a home priced at J$14m or less. [1]
A greenhouse needs a capable grower, suitable crops and paying buyers. Revenue must cover inputs, labour, asset charges, crop losses and replacement costs before it becomes household income.
Jamaican precedent: the World Bank’s REDI account describes greenhouse growers in Content, Manchester, supported by training, irrigation and links to hotel buyers. This is another project’s experience. [2]
Homes and farms need different service levels. Water storage, irrigation, drainage, solar and backup power must be sized and maintained for their actual use.
Jamaican context: the 2025 SMART Energy announcement includes solar, battery storage and rainwater harvesting. [1]
02 / Who it is for
The current planning focus is households seeking to buy a home through an affordable mortgage route, including eligible NHT contributors. The income band, deposit capacity and buyer eligibility criteria are not yet agreed.
Willing growers would run the greenhouses with agronomy, training and marketing support. A home purchase is not being presented as an obligation to farm: resident participation and eligibility for non-resident growers still need agreement.
A designated estate or service operator would maintain shared water, energy and common areas. The operator, asset ownership and charges are not yet agreed; residents and growers are distinct from the organisations delivering these services.
03 / What is proposed
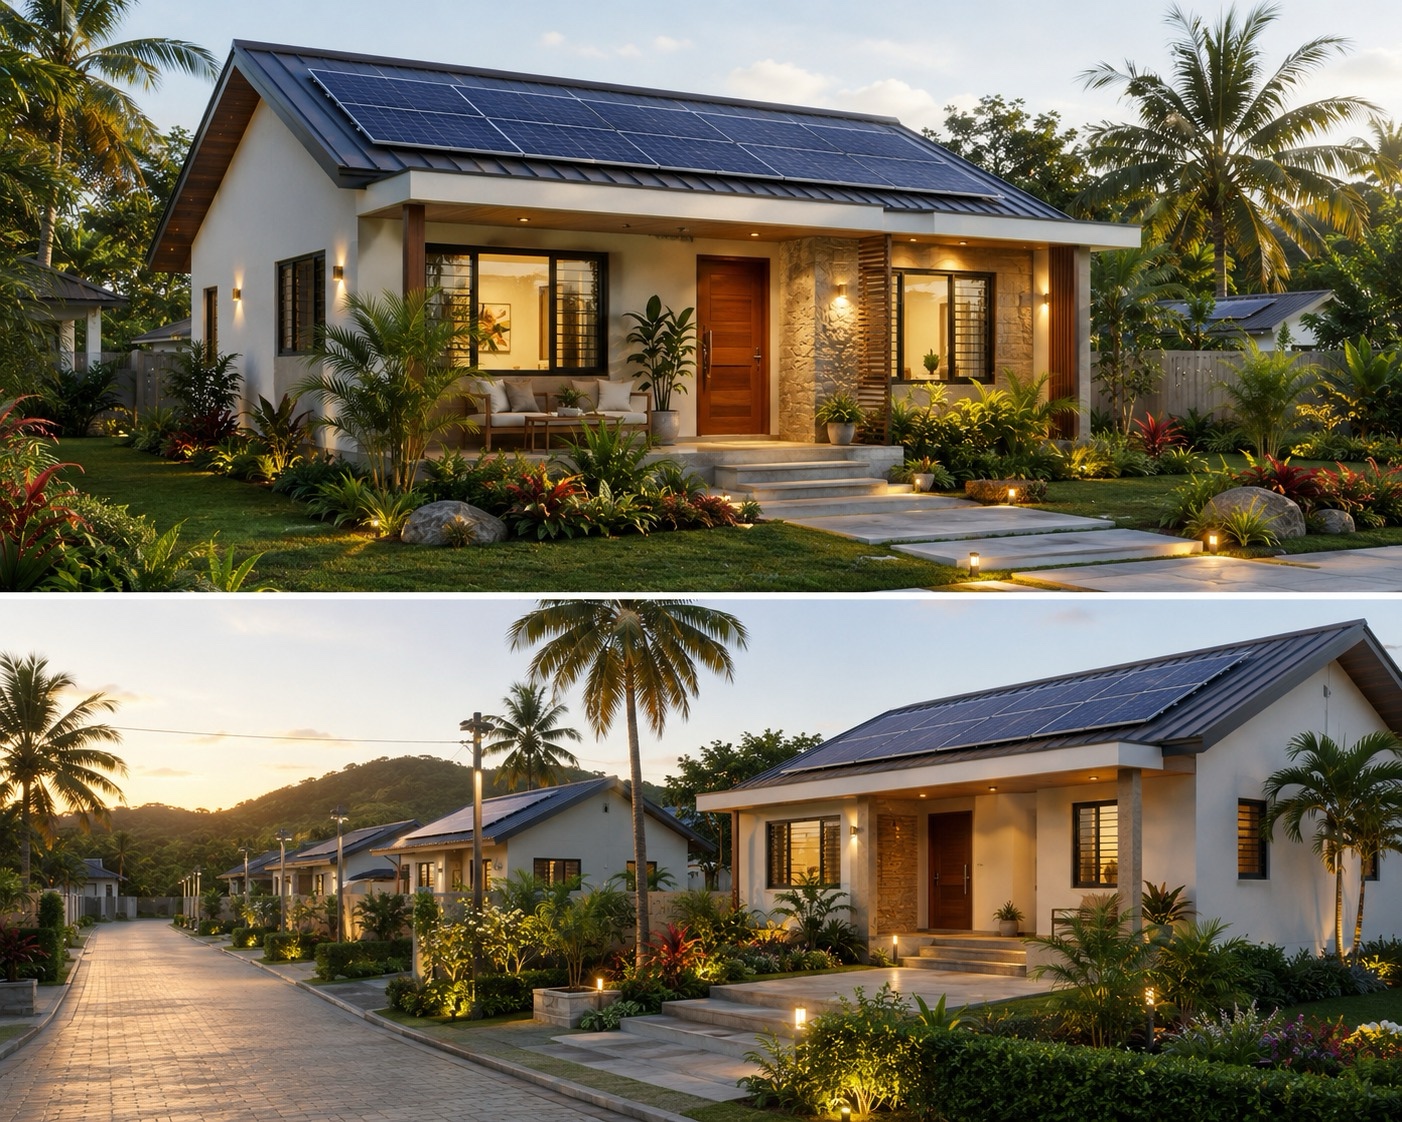
The proposed “1+1” model links housing and agriculture: one home linked to one greenhouse. The working greenhouse size is 8 × 30 metres (240 m²). This is a planning basis, not an approved specification or sales package.
The working arrangement is for a separate agricultural asset owner to fund the greenhouse and make it available to a grower for a charge. This could keep the productive asset outside the residential mortgage. Ownership, charges and grower rights are proposals, not signed arrangements.
The physical plan would need homes, growing areas, irrigation and water storage, access and drainage, solar where justified, and space for nursery, packing and produce handling. Agronomy, maintenance and sales support connect the facilities into an operating business.
04 / Where and when
Site control, planning approvals and the first-phase scope remain to be confirmed. NHT participation, purchaser finance and produce-purchase arrangements are not secured. Homes are not currently offered for sale.
The financial model includes pilot and larger-scale scenarios. These are feasibility cases, not an agreed construction programme or evidence of future farming income.
Confirm landowner authority, title, survey, access, planning constraints, water and local buyer demand. This determines whether a pilot can fit and who it could serve.
Obtain construction and infrastructure costs, test household affordability, and agree a greenhouse operating proposal with realistic crop and buyer evidence.
Set responsibilities, secure the required permissions and finance, and agree contracts before committing to construction. A programme follows these decisions.
The development review calls for crop, cost and customer evidence before expansion. No timetable is promised while those dependencies remain open.
05 / How it would work
| Element | Proposed payment and ownership | Who operates it / what remains open |
|---|---|---|
| Land and planning | A purchase, lease or land partnership would establish control. Land price, early professional costs and funding are not agreed. | Landowner, legal adviser and planning team. Title, mandate, survey, access and approvals route must be established. |
| Homes and construction | A developer would fund construction; buyers would purchase with deposits and approved mortgage finance. Home sales are modelled; no rental arrangement is agreed. | Appointed developer, builder and professionals. Designs, costs, title arrangements, funding and purchaser terms remain open. |
| Greenhouses and crops | The working option is separate agricultural ownership, with growers paying an asset charge and service fees. Equipment finance, grower working capital and charges are not agreed. | Growers supported by an agricultural operator. Crop plans, agronomy, packing, marketing and buyer contracts must be established. |
| Energy, water and common areas | Separate budgets for household, farm and shared assets. Capital funding, ownership, metering and recurring charges must be allocated. | Specialist providers and an estate/service manager. Maintenance standards, reserves, tariffs and appointments remain open. |
NHT and other finance routes are being assessed. Project-specific agreements are required for any mortgage, development loan, bulk housing purchase or produce sale.
06 / The next conversation
We welcome an initial discussion with the National Housing Trust about how this integrated housing proposal could meet contributor needs and what evidence would be required for further consideration.
Discuss the intended buyer profile, acceptable housing costs, eligibility and the treatment of household income and recurring charges.
Establish which NHT route, if any, could fit the eventual land arrangements and delivery structure. Housing finance and agricultural assets need separate consideration.
Clarify the required site information, designs, infrastructure scope, cost plan and developer capability before a formal proposal progresses.
The next useful NHT conversation is about buyer affordability, programme fit and the information needed for consideration. Supporting proposals should state assumptions, exclusions and the evidence behind costs.
Investment discussions will use a separate pitch deck and supporting financial information. This website is not an investment offer.
Project & Partnership Overview
Eight sections covering the development proposal, household needs, project status and the route to further discussion. This remains a discussion document, not an investment or housing offer.
Start a conversation
For NHT and other institutional enquiries, tell us your role, the part of the proposal you would like to discuss, and the information needed for an initial review.
Please keep an initial message brief. Land documents, financial records and other confidential material should be discussed through an agreed channel.
Introduce your organisation and the part of the proposed development you would like to discuss.
Opens your email app.
These sources explain the wider context, not commitments to Incredible Jamaica.
Sources reviewed 26 September 2026.